
Annual Report 2025-2026
Bank for the Aspiring Indians
Where Every Aspiration Finds Its Heart.
Bank for the Aspiring Indians
Where Every Aspiration Finds Its Heart.
India’s growth is fundamentally driven by the economic ambitions of its people. Across the nation, a profound shift is being noticed— families securing their futures through systematic savings and robust protection, entrepreneurs expanding their enterprises and farmers accessing productive capital to enhance yields. Today, priorities like home ownership, asset creation, education, and long-term planning are vital goals for a rapidly rising aspirational population. These evolving dynamics demand more than basic credit access; they require comprehensive banking solutions that support every stage of financial progression.
Ujjivan SFB is engineered precisely to address these shifting dynamics. The Bank serves customers across a full spectrum of savings, credit, investments, protection, and transaction banking. The product offerings spans across micro-banking, housing, MSME, agriculture, gold loan, vehicle finance, retail liabilities, Trust, Association, Society and Club (TASC) and Retail Institution and Government Banking (RIGB). It’s distribution model seamlessly integrates physical, assisted, and digital channels, ensuring customers engage precisely at their level of financial familiarity.
As modern India’s aspirations scale, Ujjivan SFB expands alongside them - ensuring every dream finds its home, and every aspiration finds its heart.
From the Chairman's Desk
Perspective on a Changing Banking Landscape
Mr. Banavar Anantharamaiah Prabhakar
Chairman
India’s banking sector continued to play an important role in supporting economic growth, expanding financial access and deepening inclusion across customer segments. During FY 2025- 26, the industry benefited from healthy credit demand, improving liquidity conditions and accelerating digital adoption, while maintaining a strong focus on risk management and deposit mobilisation.
From the Managing Director & CEO’s Desk
The Road Ahead: Purpose, Progress and Possibility
Mr. Sanjeev Nautiyal
Managing Director and CEO
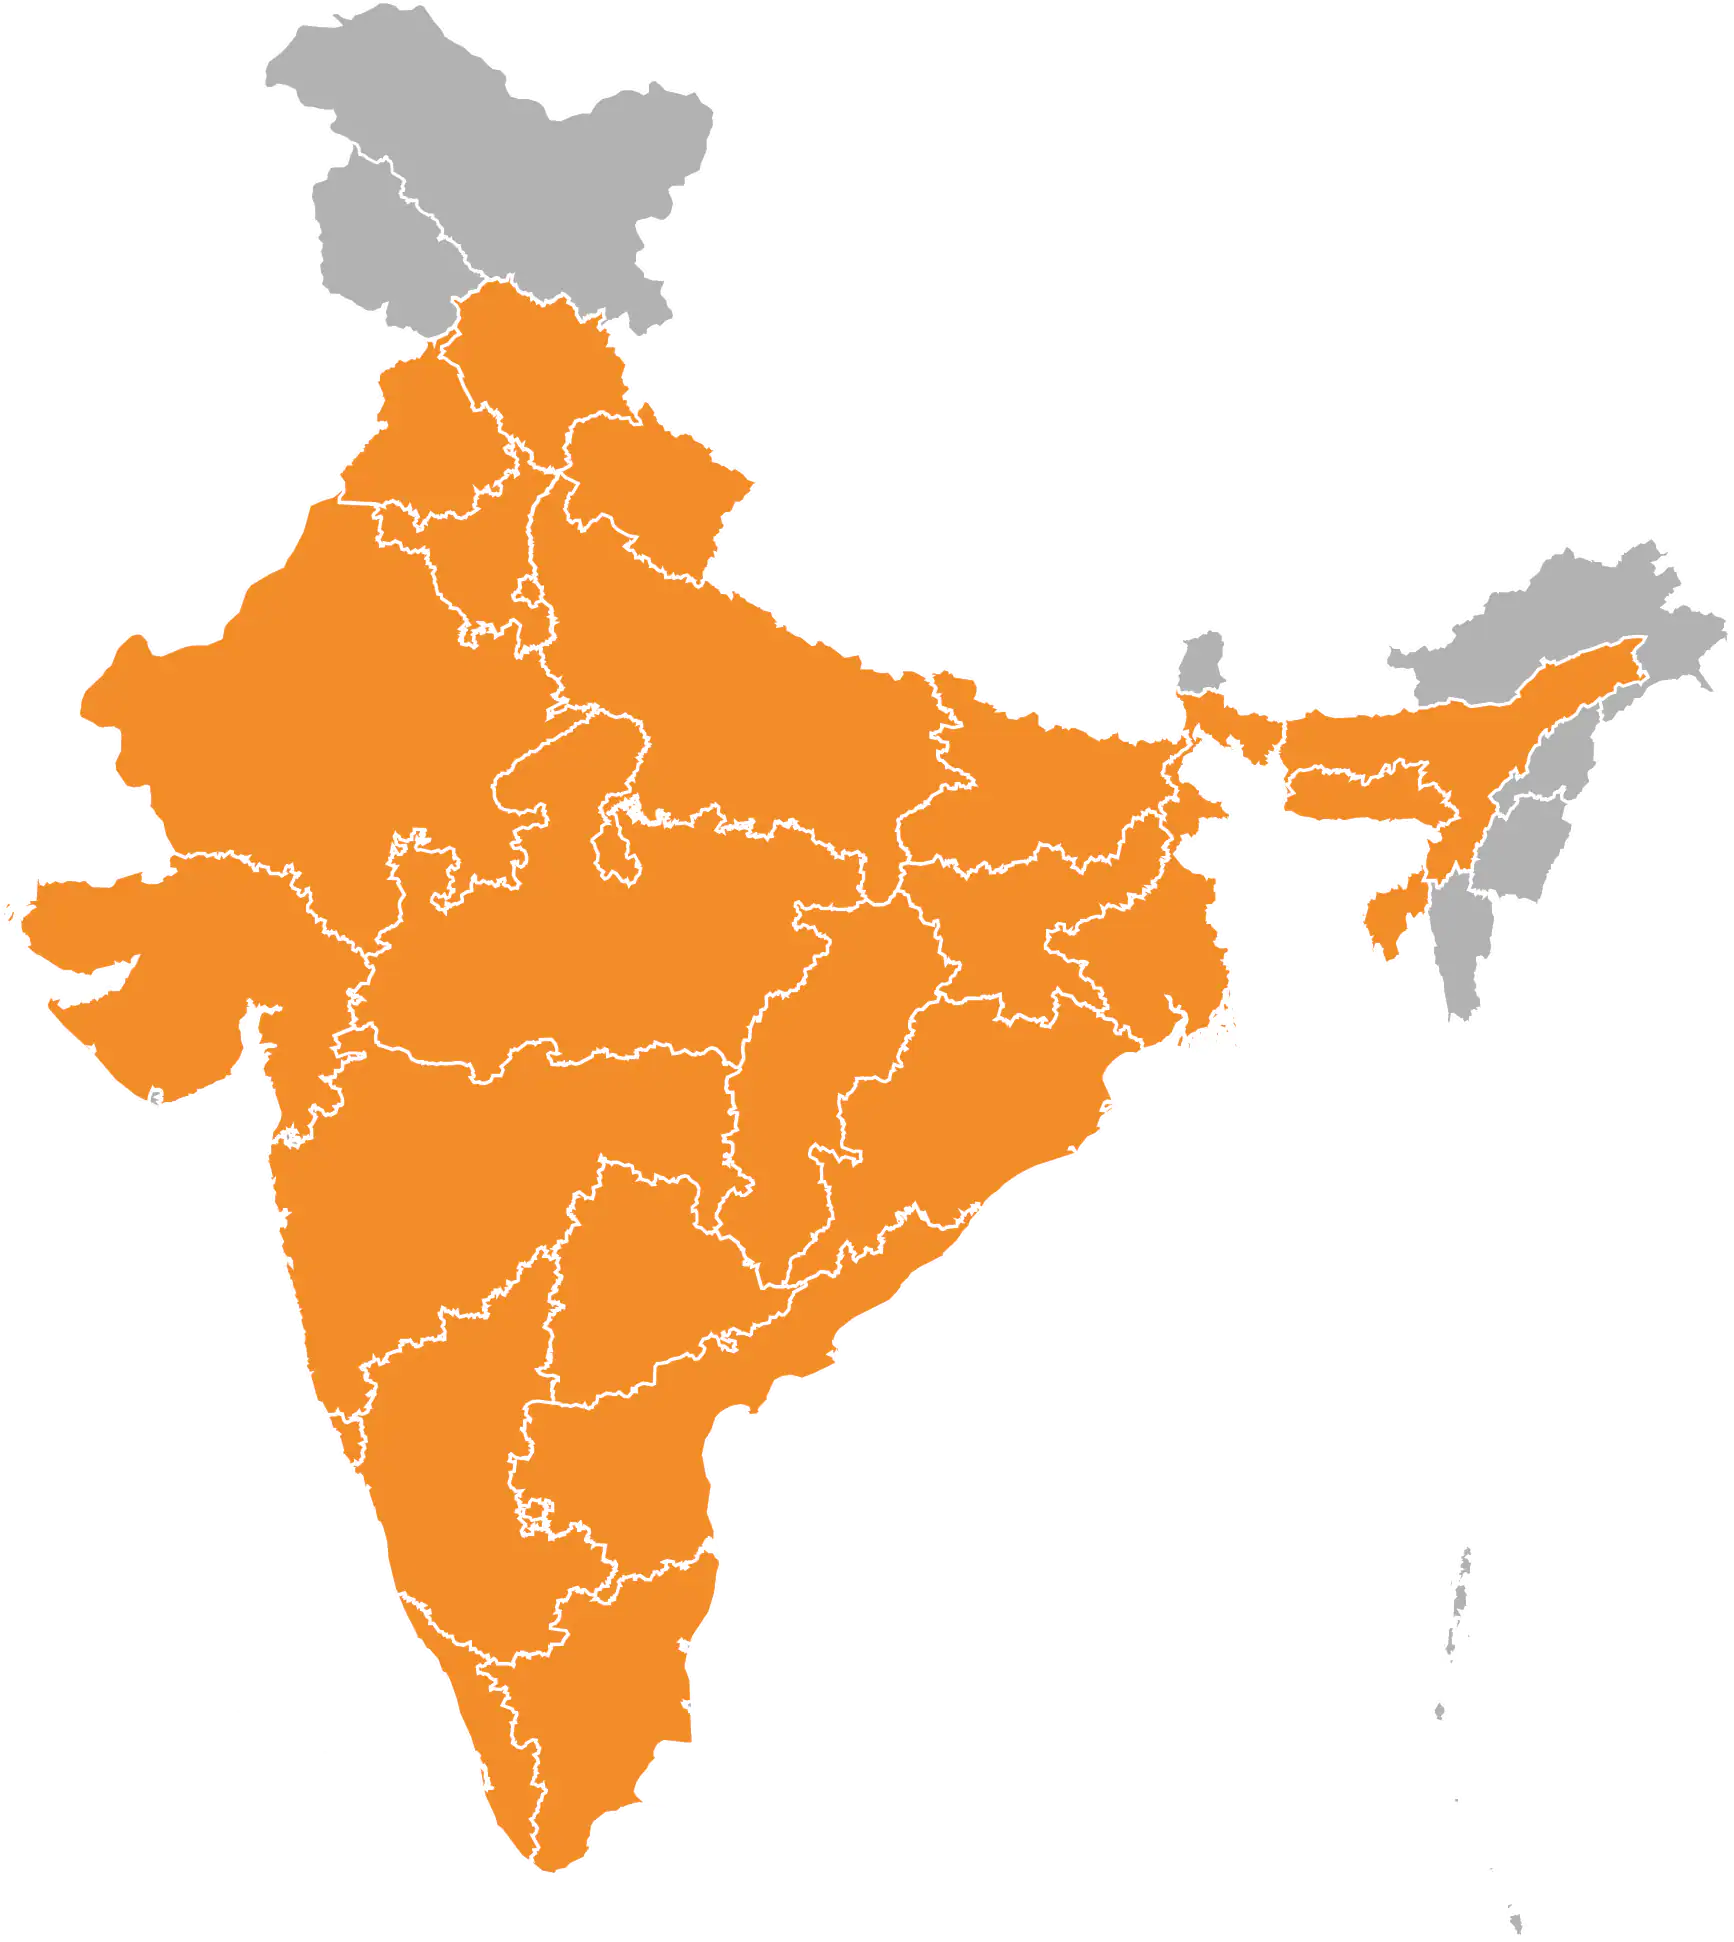
FY 2025-26 marked a significant milestone in the transformative journey of the Bank. Our branch network which covers 26 states & UT, reached 776, with net addition of 23 branches. Having incubated multiple secured lending products in the previous years, we significantly scaled up the reach of these new products.
Geographical Presence
Reaching Aspirations Across India
Ujjivan SFB’s distribution footprint is structured to balance scale with accessibility, enabling reach across to the mass affluent customer segments. This network ensures proximity to customers while supporting efficient service delivery through an integrated physical and digital model.
Presence across
0
States and Union Territories
Network spanning
0
Branches and 335 districts
Supported by
0
Unbanked Rural Centres (URCs) and assisted access points
Enabling last-mile connectivity with
0+
Electronic Collection Points (ECP)
Branches
States With branch network
2
2
19
39
14
6
39
67
61
17
1
8
100
21
25
5
13
59
60
5
1
94
3
20
94
1
Note: Map not to scale
Branches
States With branch network
Digital Future
Serving Customers Through Multiple Channels
The Bank's channel strategy is designed around the evolving expectations of customers who increasingly seek accessibility, convenience and consistency across physical and digital touchpoints. As banking journeys become more integrated, the Bank has continued to strengthen its omni-channel model to support seamless engagement across acquisition, onboarding, servicing, payments and collections.
Serving the Financial Needs of Aspiring India
1 / 10 - Micro Banking
The First Step Forward
The Micro Banking business operates through group and individual lending models with strong local presence, enabling consistent customer engagement, effective monitoring and controlled portfolio quality. During the year, the Bank adopted a calibrated growth strategy with sharper focus on portfolio quality, prudent customer selection and tighter control over borrower behaviour, reflecting a conscious shift towards sustainable growth underpinned by disciplined risk management.
Prosperity Beyond the Harvest
Agriculture Banking continues to scale as a secured lending vertical, aligned with the Bank's strategy of diversifying the portfolio and supporting customer progression into higher-ticket products. The business primarily serves progressive farmers and core agriculture segments, including allied activities such as fisheries and poultry, with lending calibrated to landholding, crop patterns and income potential. It also plays a defined role in enabling customer graduation from Micro Banking and other retail segments into secured lending.
Enterprise, Ambition and Achievement
MSME is positioned as a relationship-led secured lending business, focused on serving Micro and Small enterprises through structured credit and integrated banking solutions. The portfolio spans Loan Against Property, Working Capital and Supply Chain Finance, supporting businesses across manufacturing, trading and service sector. The business is progressively moving towards deeper engagement with customers, with a shift from transactional lending to multi-product relationships.
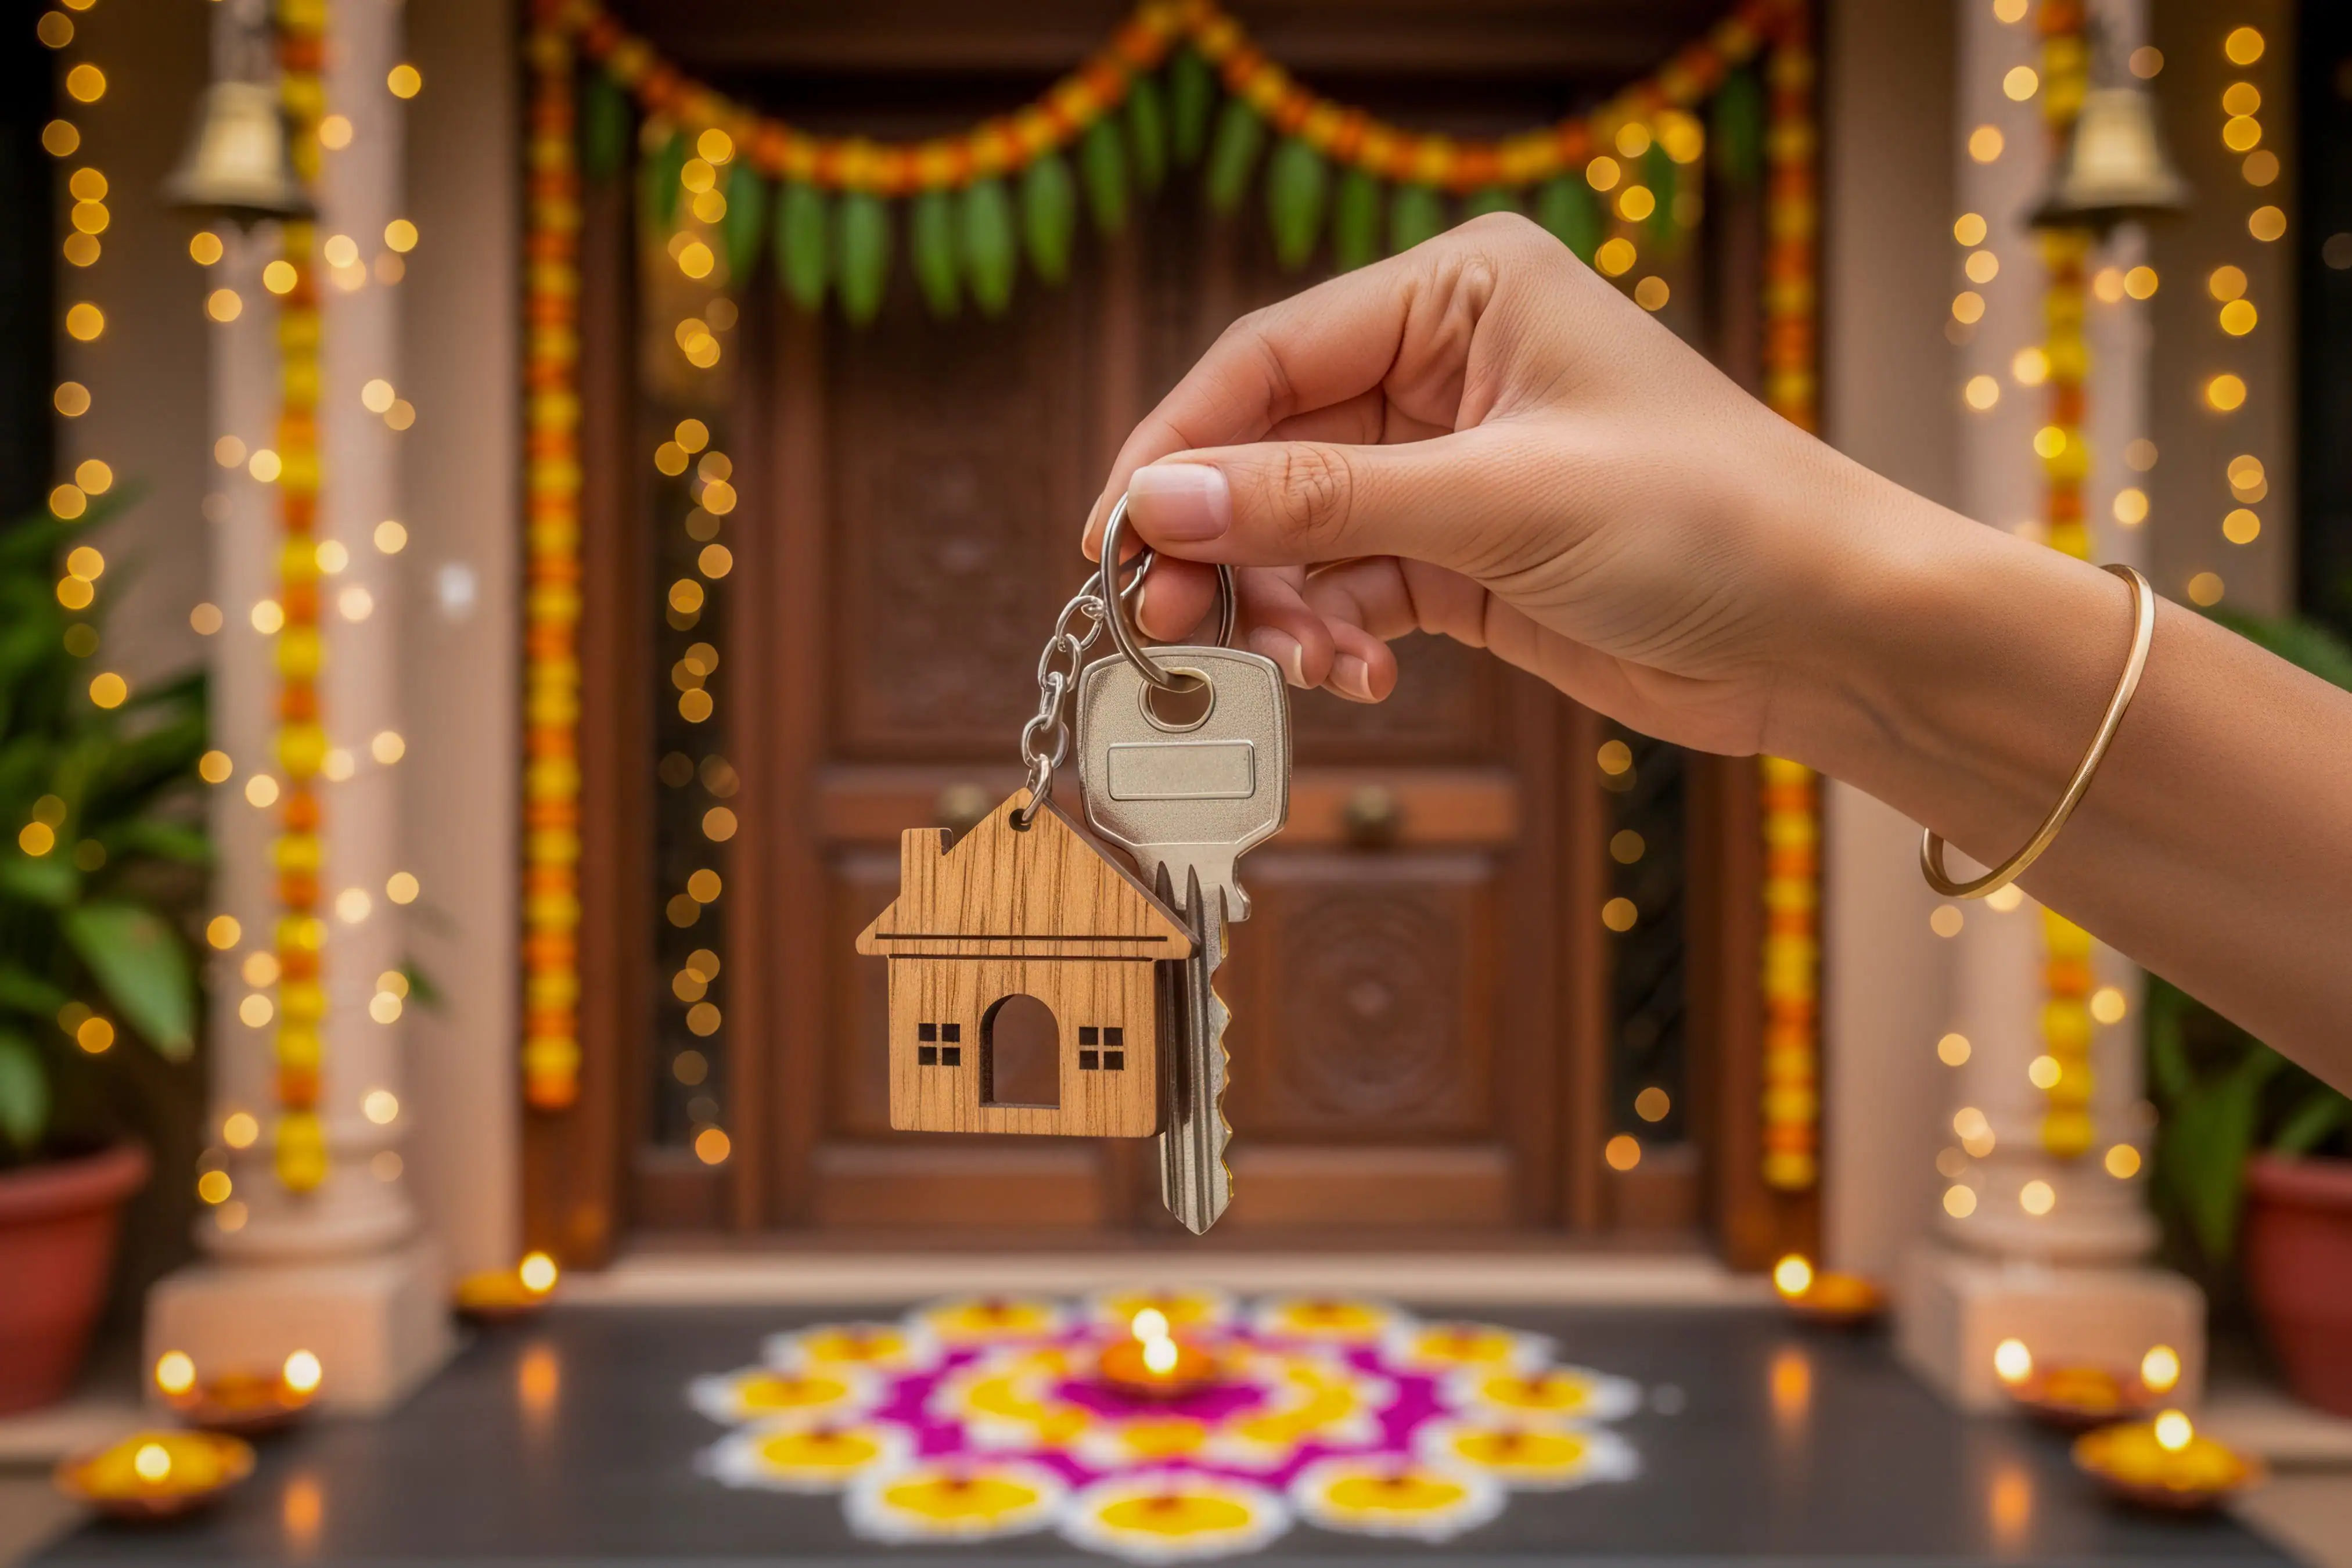
The Security of Home Ownership
Housing and Micro-mortgages continue to be key contributors to the Bank’s secured lending portfolio, with a clear role in supporting customer progression from informal credit to long-term asset creation and enabling home ownership for India’s emerging, aspiration- driven segments. The business serves customers across EWS, LIG and MIG segments in Tier II, III and IV markets, with a strong focus on first-time home owners and self-employed profiles. Micro Mortgages and Affordable Housing together enable coverage across the customer lifecycle, supporting transition from initial credit access to home ownership.
Mobility in Pursuit of Progress
Vehicle Finance is a secured, high-yield business focused on enabling mobility and supporting customer progression into formal credit. The business primarily caters to customers purchasing their first two-wheeler vehicle through financing or upgrading to better two-wheeler vehicles, including customers graduating from the Bank’s existing Group Loan (GL) and Individual Loan (IL) customer base. Operating across 11 major states, the business remains focused on semi-urban and up-country markets, while gradually expanding its presence across select Tier-I locations.
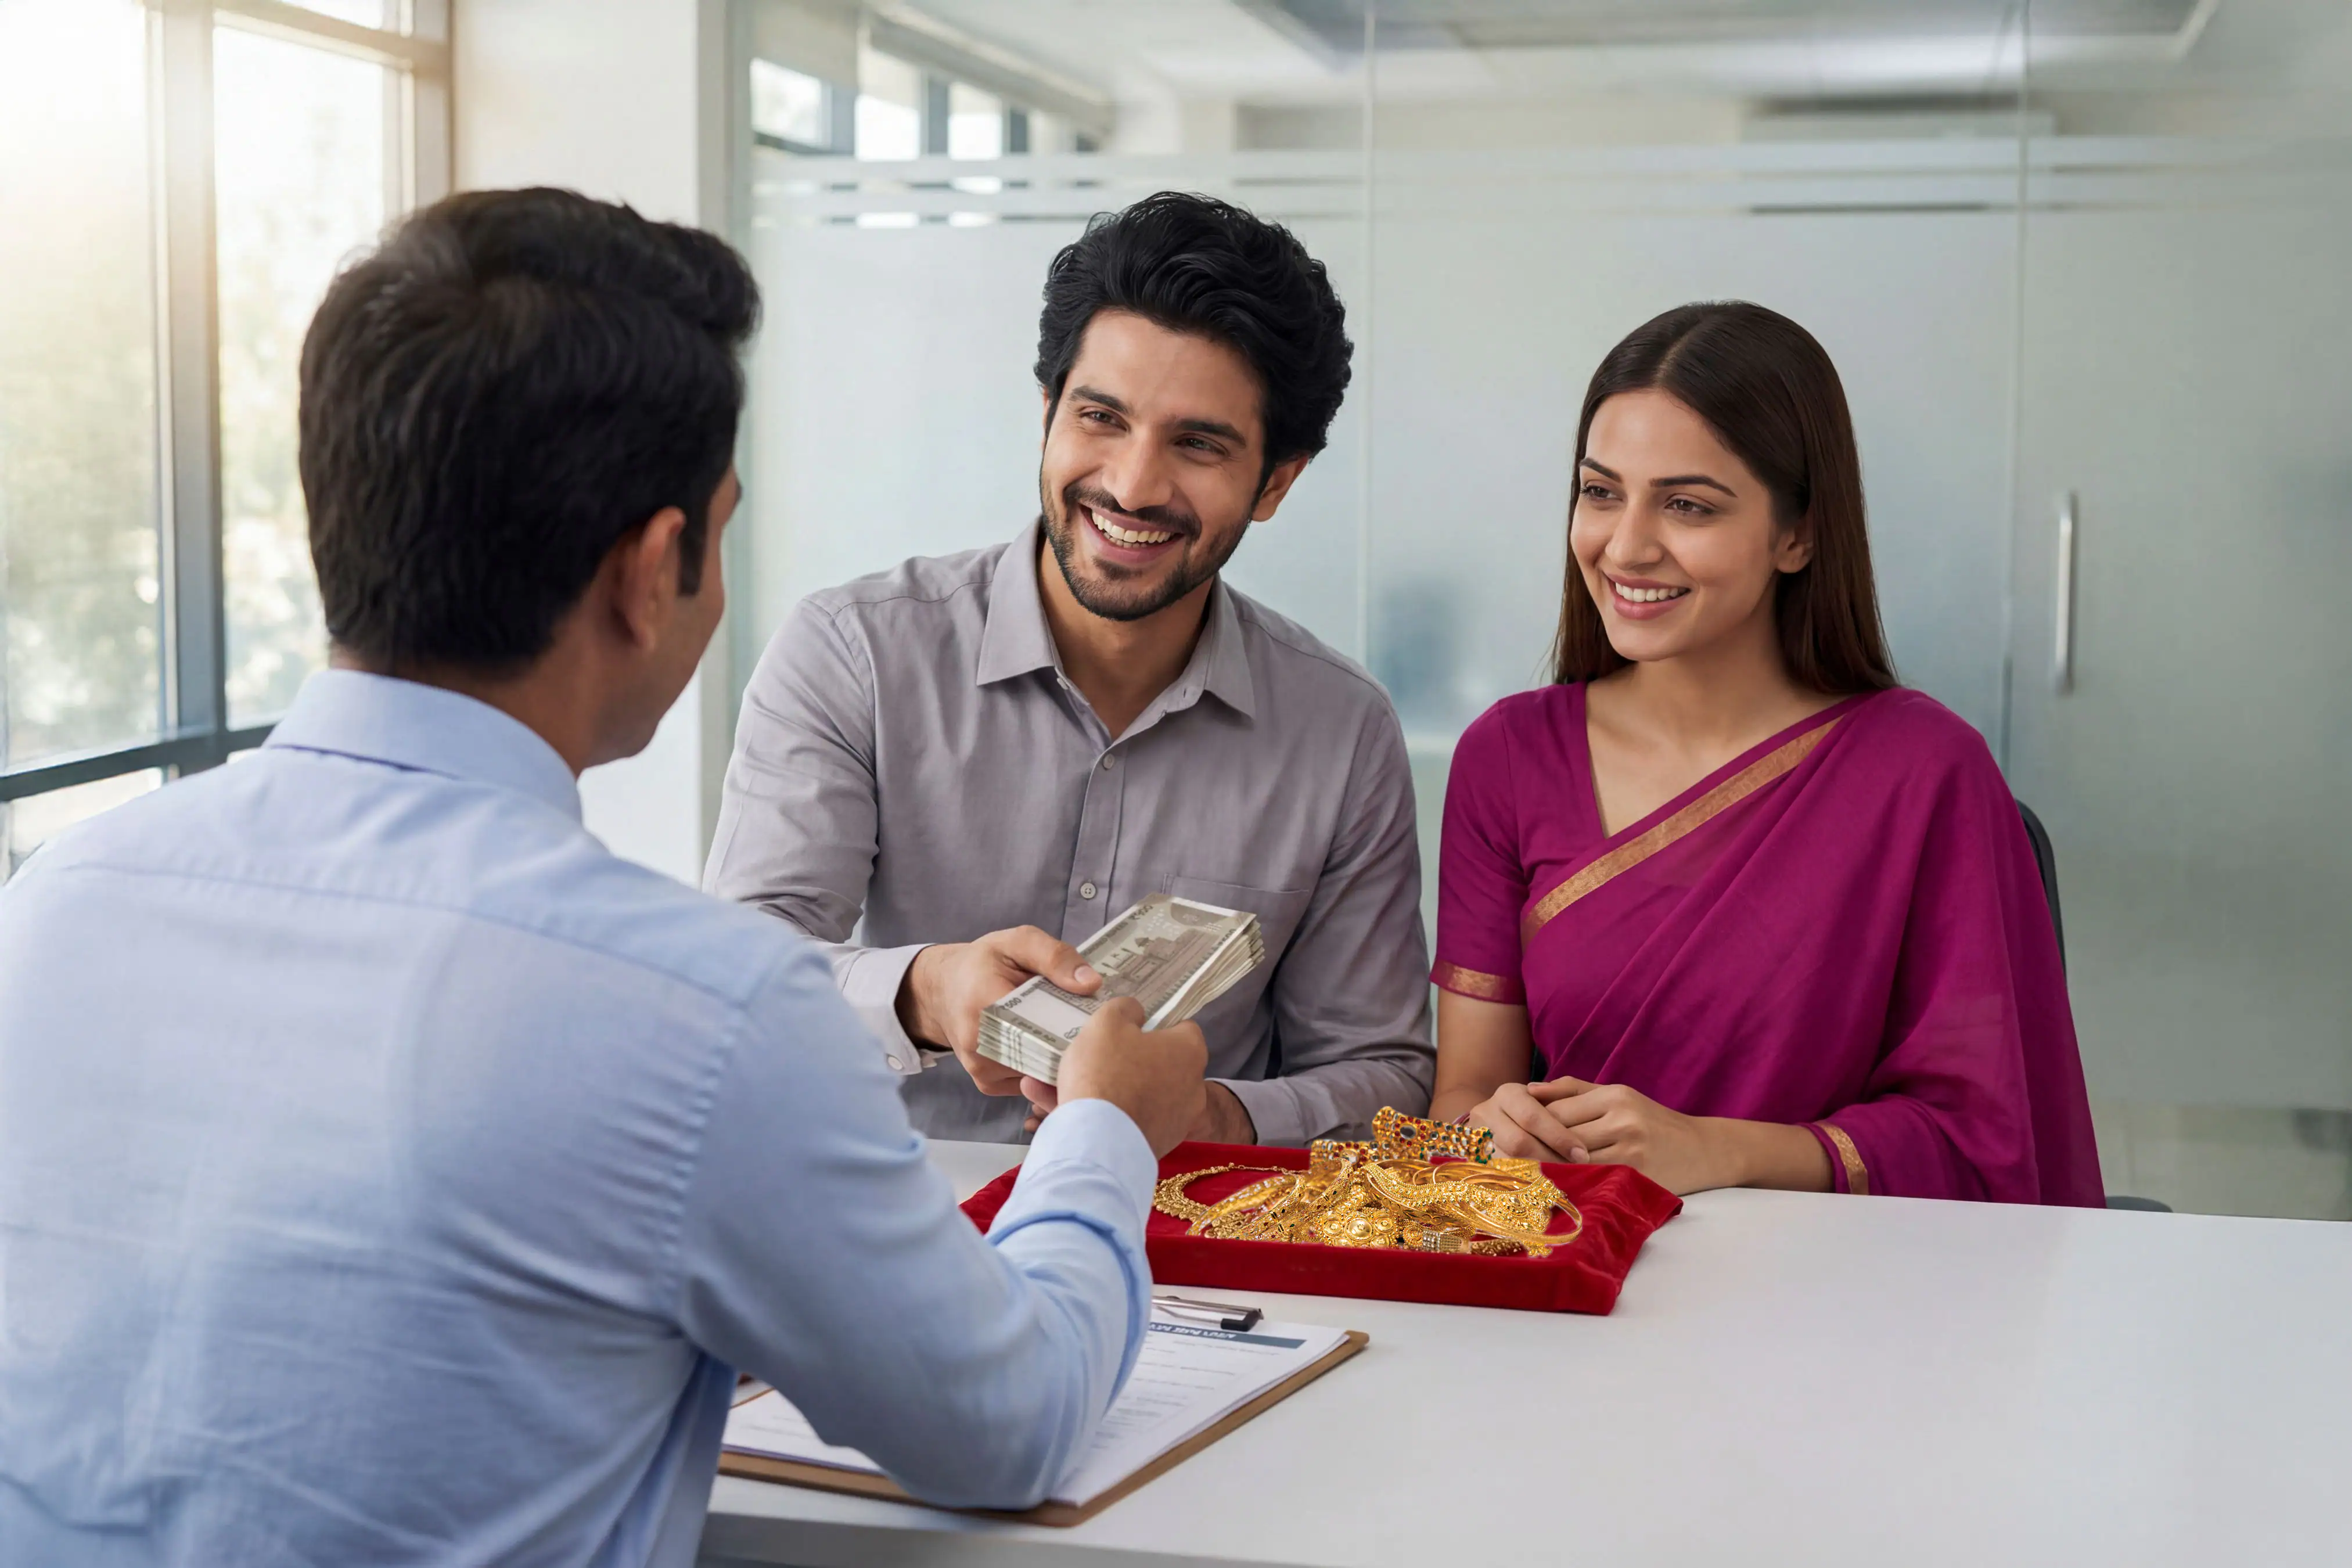
Financial Flexibility When It Matters
Gold Loan is a secured, short-tenor lending product focused on providing quick liquidity against gold collateral, with a clear role in strengthening the Bank’s secured portfolio. Under the Gold Ujjivan SFB proposition, the business caters to a wide customer base across agriculture, self-employed and salaried segments, offering flexible repayment options aligned to diverse income patterns. It also supports the Bank’s objective of expanding access to formal credit while enabling customers to unlock value from existing assets.
Partnerships with Broader Purpose
FIGB serves as the Bank’s institutional banking platform, with a defined role in balancing the balance sheet across assets and liabilities while strengthening relationships with financial institutions and government entities. The business supports both liquidity management and portfolio diversification, with exposure to NBFCs, MFIs, HFCs and, more recently, mid-corporates. It also plays an important role in liability mobilisation and maintaining key balance sheet metrics, while enabling the Bank to expand beyond its core retail segments.
Trust at the Centre of Relationships
Retail Liabilities remains central to the Bank's funding strategy, with a clear role in building a granular and stable deposit franchise while strengthening Current Account Savings Account (CASA). The business is anchored in retail deposits, supported by a calibrated approach to pricing, product design and customer acquisition. Branch Banking continues to provide scale through local presence and customer engagement, while the Trusts, Associations, Societies and Clubs (TASC) segment complements this by contributing stable institutional balances and deepening relationship-led sourcing.
Stewardship Through Market Cycles
Treasury is central to the Bank's balance sheet management, with a defined role in maintaining liquidity, optimising funding costs and supporting margin stability. The function actively manages asset-liability positioning, ensuring adherence to regulatory requirements while enabling efficient deployment of funds across varying market conditions. Operations are anchored in a multi-asset dealing framework, supported by robust infrastructure and risk controls, enabling continuous monitoring and timely execution.
Choices for Every Financial Need
The Third-Party Products (TPP) business has evolved into a meaningful contributor to the Bank’s overall customer proposition, strengthening both fee income and relationship depth. The portfolio enables the Bank to offer solutions beyond core banking, particularly in protection and financial security, while increasing customer engagement and wallet share. Insurance products support customer stickiness, while investment offerings such as mutual fund SIPs and Demat accounts contribute to improving Current Account Savings Account (CASA) balances. During the year, the business scaled materially, with income increasing to ~₹175 Crores, highlighting its growing relevance within the Bank's diversified revenue streams.
Turning Aspirations into Outcomes
Ujjivan SFB focuses on ensuring that financial access leads to visible progress. By combining relevant products with consistent service delivery, the Bank enables customers to convert opportunities into outcomes— whether through income generation, asset creation or improved financial stability. The emphasis remains on execution, where every interaction supports forward movement in the customer’s financial journey.
Sustaining Aspirations Responsibly
Growth at Ujjivan SFB is built on discipline. The Bank integrates strong risk management, responsible lending and governance into its day-to-day operations to ensure that expansion remains stable and controlled. This approach safeguards both customer interests and portfolio quality, enabling progress to be sustained over time.
Board of Directors
Experience Shaping Direction
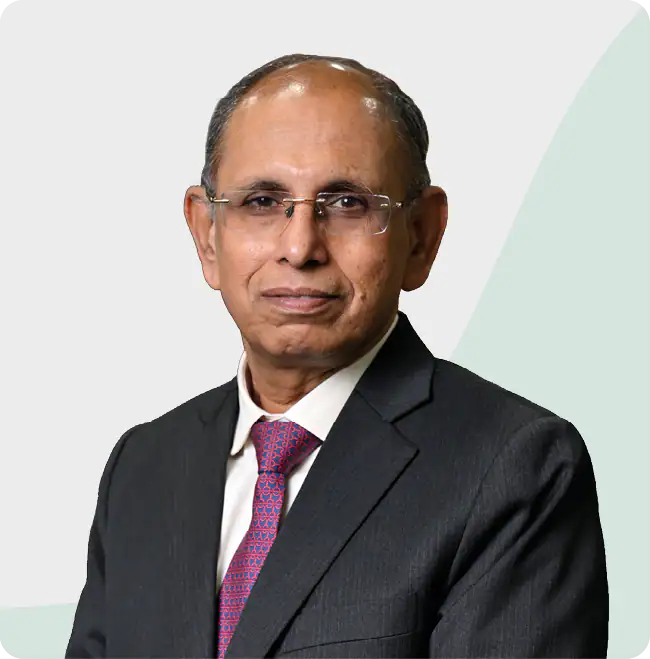
Mr. Banavar Anantharamaiah Prabhakar
Part-Time Chairman and Independent Director

Mr. Sanjeev Nautiyal
Managing Director & Chief Executive Officer
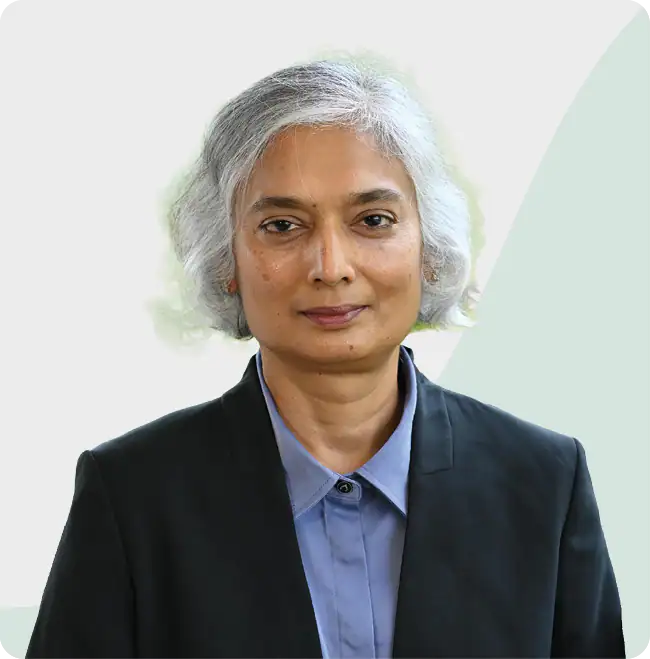
Ms. Carol Furtado
Whole-time Executive Director
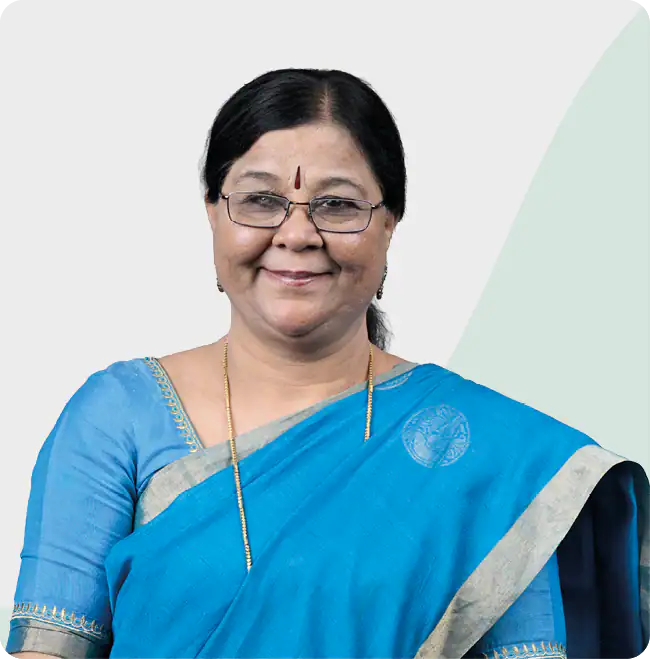
Ms. Sudha Suresh
Independent Director

Mr. Rajesh Jogi
Independent Director

Ms. Rajni Mishra
Independent Director

Mr. Ravichandran Venkataraman
Independent Director

Ms. Mona Kachhwaha
Independent Director
Mr. Aniruddha Paul
Independent Director
Leadership Team
Leading a Bank of Many Aspirations
Mr. Sanjeev Nautiyal
Managing Director and Chief Executive Officer

Ms. Carol Kripanayana Furtado
Whole-time Executive Director

Mr. Sadananda Balakrishna Kamath
Chief Financial Officer
Mr. Ashish Goel
Chief Credit Officer
Mr. Martin Pampilly S
Chief Operating Officer
Mr. Rajaneesh Hosakoppa Rudresha
Chief Compliance Officer

Mr. Brajesh Joseph Cherian
Chief Risk Officer
Mr. Pankaj Gupta
Chief Digital Officer
Ms. Chandralekha Chaudhuri
Head Of Human Resources
Mr. Deepak Agarwal
Head of Strategy and Transformation
Mr. Mangesh Ramesh Mahale
Chief Technology Officer

Mr. Rajeev Padmanabh Pawar
Head of treasury

Mr. Hitendra Nath Jha
Head Retail Liabilities, TASC and TPP
Mr. Vibhas Chandra
Head -Micro Banking and Gold Loans
Mr. Umesh Arora
Head of Emerging Business
Mr. Pradeep B
Business Head-Housing Loans and Micro Mortgages

Mr. Parag Kumar Srivastava
Head of Financial Institutions and Government Banking Group
Mr. Premkumar G
Business Head-Vehicle Finance
Mr. Murali Chari
Business Head-Agriculture Banking
Mr. Lakshman Velayutham
Chief Marketing Officer

Mr. Ayan Sarkar
Head Of Operations
Mr. Srikumar Vadake Varieth
Chief Legal Officer

Ms. Vijayalakshmi Muddu
Head of Internal Audit

Mr. Ratan Jyoti
Chief Information Security Officer

Mr. John Christy A
Chief Vigilance Officer

Mr. Sanjeev Barnwal
Company Secretary and Head of Regulatory Framework

Mr. Vijayesh Kumar Pandey
Head of Admin and Infrastructure

Mr. Suresha C
Head of Customer Experience

Mr. Arnabjeet Banerjee
Head-Alliance and Electronic Payments

Mr. Mohd Shakil Khan
Head of Collections