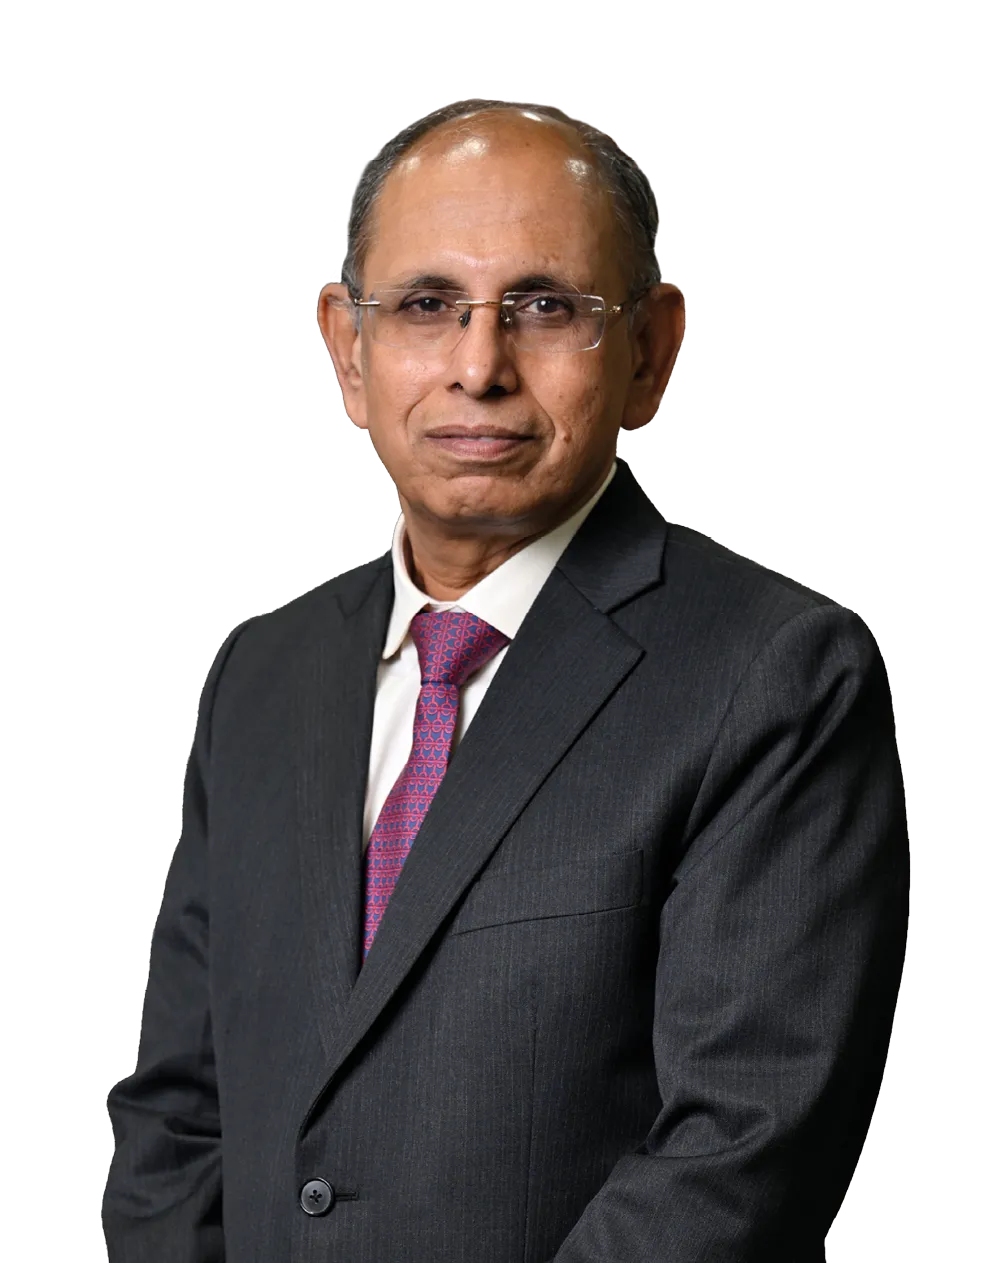
Dear Shareholders,
Ujjivan was founded with a clear and enduring purpose: to make financial services accessible, responsible and relevant for those who have traditionally remained underserved. FY 2025–26 was a year of steady progress, one that required resilience and disciplined decision-making as we continued to strengthen our foundations and advance our mission of financial inclusion.
Operating Environment
The global environment remained uncertain through FY 2025-26, shaped by geopolitical tensions and shifting trade dynamics. India, however, continued to demonstrate resilience: GDP growth for the year came in at 7.6%, anchored by domestic demand, government capital expenditure and policy continuity. Consumer Price Index (CPI) inflation declined sharply to 2.1%, well within the RBI’s target band of 2–6%. This allowed the Monetary Policy Committee to pivot decisively, cutting the repo rate by a cumulative 125 basis points during FY 2025-26, from 6.50% to 5.25%, the steepest easing cycle in recent years. Lower interest rates and improved household cash flows had a direct bearing on our business. Repayment capacity improved, and demand strengthened across micro-banking and affordable housing, our two largest segments.
India’s banking sector continued to play an important role in supporting economic growth, expanding financial access and deepening inclusion across customer segments. During FY 2025-26, the industry benefited from healthy credit demand, improving liquidity conditions and accelerating digital adoption, while maintaining a strong focus on risk management and deposit mobilisation. The microfinance sector, which had experienced stress during FY 2024-25, began to stabilise as industry-led guardrails strengthened credit discipline and supported an improvement in collection trends. Demand across affordable housing, MSME lending and other secured retail segments also remained encouraging, creating opportunities for banks pursuing diversified and sustainable growth.
Performance Overview
FY 2025-26 was a year of stable operating performance alongside continued investment in long-term capabilities, a balance we view as essential to building a franchise that performs consistently across cycles. Building on the progress made in FY 2024-25, we continued to strengthen our balance sheet, diversify our portfolio and improve the quality of growth across the franchise.
Our total balance sheet increased from ₹47,689 Crores in FY 2024-25 to ₹57,541 Crores in FY 2025-26, underscoring the steady expansion of our franchise and the momentum across both assets and liabilities. Net Interest Income increased to ₹3,871 Crores in FY 2025-26 from ₹3,636 Crores in FY 2024-25, driven by growth in the loan portfolio and a steady Net Interest Margin (NIM). Pre-Provision Operating Profit improved to ₹1,710 Crores from ₹1,689 Crores in the previous year, supported by business growth, operating efficiencies and continued investments in productivity-enhancing digital capabilities.
Profit After Tax stood at ₹693 Crores in FY 2025-26, compared with ₹726 Crores in FY 2024-25, reflecting elevated credit costs and higher provisioning requirements, particularly during the earlier part of the year amid stress in the microfinance sector. However, underlying operating performance improved progressively through the year, supported by portfolio diversification, improving collection trends and strengthening asset quality indicators.
Return on Assets stood at 1.4%, compared with 1.6% in FY 2024-25, while Return on Equity stood at 10.9%, compared with 12.4% in the previous year. These metrics were impacted by elevated provisioning during the year and should be viewed in the context of our prudent approach to balance sheet strengthening and risk management. Net Interest Margin remained healthy at 8.1%, reflecting the resilience of our core lending franchise.
Net Worth increased to ₹6,816 Crores from ₹6,083 Crores in FY 2024-25, supported by sustained profitability and internal capital generation. Our Capital Adequacy Ratio remained robust at 21.14% for FY 2025-26, providing a strong foundation to support future growth, portfolio diversification and long-term value creation.
Strengthening the Deposit Franchise
Our total deposits grew from ₹37,630 Crores in FY 2024-25 to ₹45,668 Crores in FY 2025-26, reflecting the resilience of our deposit franchise and our ability to attract and retain granular retail deposits in a competitive market. Retail term deposits and CASA together reached ₹31,955 Crores, and our CASA ratio improved to 28.6% from 25.5% in FY 2024-25. Liquidity remained comfortable, with a Liquidity Coverage Ratio of 142% as at March 2026. What is encouraging is not just the growth itself, but the quality of this growth. The steady build-up in retail deposits and CASA reflects increasing customer confidence and a more balanced funding mix. This provides us with greater stability in a dynamic interest rate environment and strengthens our ability to support asset growth in a calibrated manner. These trends, in our view, are a clear indicator of the trust our customers place in us and our continued efforts to build a sustainable and resilient funding profile.
Our Gross Loan Book grew by 27% to ₹40,655 Crores during the year, reflecting steady progress in expanding our lending product suite while remaining aligned with our risk philosophy.
An important aspect of this growth has been our continued shift towards secured lending. The secured portfolio grew by 44% to ₹20,079 Crores and now constitutes 49.4% of our overall loan book. We see this transition as central to building long-term stability and resilience, as it not only strengthens the quality of our assets but also brings greater balance to our portfolio over time.
We witnessed strong growth across multiple segments, with Affordable Housing growing 35% to ₹8,900 Crores, Micro Mortgages 118% to ₹1,577 Crores, MSME advances 58% to ₹3,230 Crores, Gold Loans 292% to ₹769 Crores, Vehicle Finance 102% to ₹944 Crores and Agri Banking 127% to ₹731 Crores. This broad-based expansion reflects the increasing diversification of our portfolio, with each of these segments contributing meaningfully to growth while reducing concentration risk and enhancing the granularity of our loan book. Our Financial Institutions Group portfolio stood at ₹3,000 Crores, further supporting diversification and providing an additional avenue for calibrated growth.
At the same time, our microfinance portfolio remained stable, with Group Loans at ₹14,696 Crores, representing 36% of the total portfolio. We believe this reflects a measured and disciplined approach, where we continue to retain our core strengths in microfinance while consciously moderating concentration and building a more balanced portfolio mix.
Asset Quality and Risk Discipline
Asset quality improved during the year, with Gross NPA moderating to 2.3% and Net NPA to 0.4%, reflecting the effectiveness of our underwriting, monitoring and collection efforts. Our Provision Coverage Ratio was maintained at 81%, reflecting what we believe is a prudent and forward-looking approach, ensuring that we remain well-prepared to navigate potential uncertainties while protecting the strength of our balance sheet.
On the other hand, collection efficiency on our overall loan book improved to 98.3% in Q4 FY 2025-26. From our perspective, this improvement is particularly encouraging, as it reflects both better borrower behaviour and the effectiveness of our on-ground engagement and risk management practices.
As we look ahead, our ambition extends beyond growth in scale. We remain focused on building a diversified, technology-enabled and customer-centric institution that advances financial inclusion while delivering operational excellence. The progress made in expanding our secured lending portfolio, strengthening our retail deposit franchise, improving asset quality and accelerating digital adoption provides a strong foundation for future growth.
Digital Progress
Technology continues to play an important role for us in extending access and improving efficiency, and we see it as a core enabler of both growth and customer experience.
During the year, 93.7% of our transactions were conducted through digital channels, underscoring the significant progress we have made in driving digital adoption and enhancing customer convenience across our franchise. This level of digital adoption gives us confidence that our customers are steadily embracing more seamless and convenient banking channels, while also allowing us to operate with greater efficiency.
We also saw encouraging progress in digital adoption across products, with 73% of our retail term deposits sourced digitally and 45% of our micro banking repayments becoming fully digital. To us, this reflects a meaningful shift in customer behaviour across both liability and lending sides, indicating that digital is now becoming embedded across segments rather than being limited to specific use cases.
Our analytics-led initiatives contributed to over ₹1,100 Crores in incremental business, while process automation helped improve efficiency and reduce operating costs. Alongside business growth, the Bank undertook an extensive cost optimisation exercise aimed at improving productivity, enhancing operational efficiency and building a more scalable organisation. A key pillar of this effort has been Project Vector, which is focused on accelerating digital adoption, streamlining processes, strengthening analytics-led decision-making and optimising the operating model across the franchise. Through greater use of alternate channels, centralisation of select operations and deeper technology integration, the Bank has enhanced customer experience, improved productivity and strengthened operating leverage. Taken together, these initiatives are helping create a more agile, technology-enabled and future-ready institution, while supporting sustainable growth, cost discipline and long-term profitability. From a broader perspective, we believe our continued progress across digital adoption, alongside our shift towards a more secured and diversified loan portfolio, improving asset quality, and a strengthening deposit franchise, is helping us build a more balanced, efficient and future-ready institution.
Key Developments
The year marked several important milestones in our journey, reflecting both the scale we have achieved and the direction in which we are evolving as an organisation. Our loan book crossed ₹40,000 Crores while our secured portfolio approached 50% of total advances. We believe this is a significant inflection point, as it reflects not just growth but a structural shift towards a more balanced and resilient portfolio. At the same time, asset quality trends improved despite earlier sectoral challenges, and digital adoption continued to scale, reinforcing our confidence in the underlying strength of our operating model.
During the year, we also crossed the milestone of serving over 100 Lakhs customers, reflecting the growing relevance of our franchise across India’s emerging segments. What stands out to us across these developments is the way multiple aspects of our business, including portfolio mix, asset quality, customer scale and digital capability, are progressing together, indicating a more integrated and sustainable growth trajectory. This is further supported by the steady strengthening of our deposit franchise over the years and our ability to navigate economic cycles with resilience, giving us confidence as we continue to build for the long term.
Strategy and Outlook
India stands at an important stage in its economic development, with rising incomes, increasing formalisation and broader access to financial services creating new opportunities across households, entrepreneurs and small businesses. The banking sector has a central role to play in this progress, not only through the provision of capital but also by fostering financial confidence, encouraging enterprise and expanding economic participation. As these trends continue to shape the operating context, we believe institutions with a clear purpose, prudent stewardship and a deep understanding of customer needs will remain well placed to create long-term value. Ujjivan’s journey has always been rooted in these principles, and we remain optimistic about the opportunities that lie ahead.
Vision for the Future
As we look ahead, our ambition extends beyond growth in scale. We remain focused on building a diversified, technology-enabled and customer-centric institution that advances financial inclusion while delivering operational excellence. The progress made in expanding our secured lending portfolio, strengthening our retail deposit franchise, improving asset quality and accelerating digital adoption provides a strong foundation for future growth. We also remain committed to leveraging analytics, automation and digital capabilities to enhance customer experience and operational efficiency. Supported by a strong capital position and continued portfolio diversification, we remain committed to creating sustainable long-term value and progressing towards our aspiration of becoming a universal bank.
Our journey has always been anchored in responsibility, and we continue to see this not as a separate agenda but as an integral part of how we operate and grow. We remain committed to financial inclusion, supporting underserved communities, and delivering responsible financial solutions. Our efforts extend to community development and environmental sustainability, and we are strengthening governance practices across our operations. As our franchise grows, these principles become more, not less, important.
Acknowledgement
I would like to express my sincere appreciation to our customers for the trust they continue to place in us, which remains the foundation of everything we do. I am equally grateful to our employees for their dedication, resilience and commitment, particularly in a year that required both discipline and adaptability. Their efforts on the ground, across functions and geographies, have been central to the progress we have made.
I also extend my thanks to our regulators, partners and shareholders for their continued guidance, confidence and support. We value the constructive engagement and long-term perspective that each of our stakeholders brings to our journey.
FY 2025–26 reinforced our belief that sustainable growth is built on strong foundations, disciplined execution and a clear sense of purpose. As we move forward, we remain committed to a bank that is financially strong and socially meaningful — one that enables aspirations, supports livelihoods and creates opportunities across India. We will continue to balance growth with prudence, scale with stability, and innovation with responsibility.
Yours sincerely,
B. A. Prabhakar
Chairman