The Impact of Interest Rate Changes on Your Home Loan
October 05, 2026
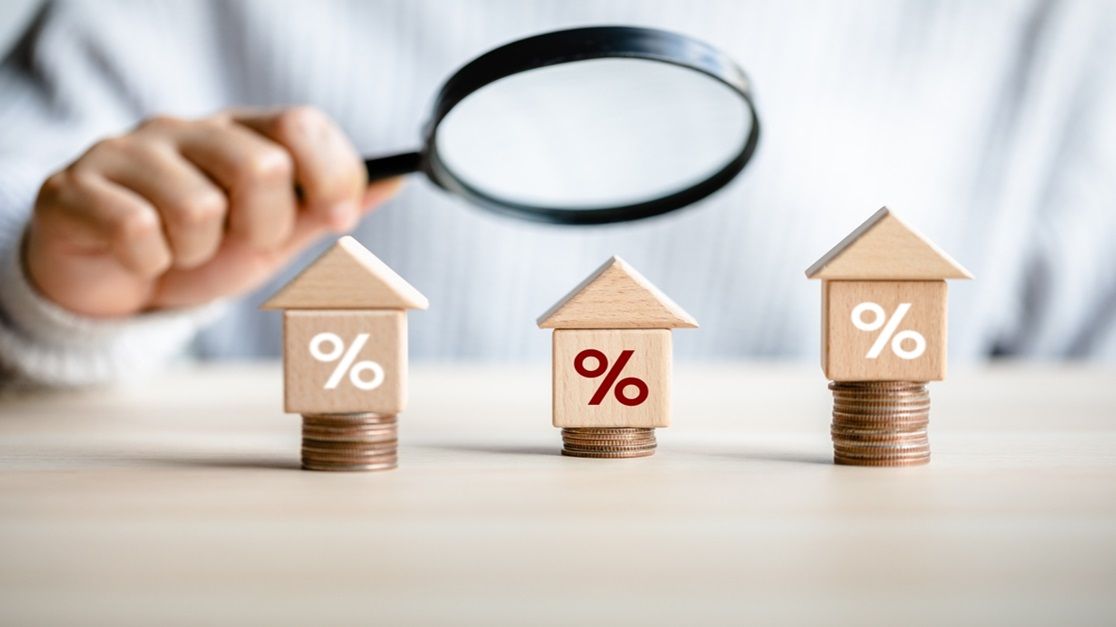
Home loan interest rate changes can affect your monthly EMI, remaining loan tenure and total interest payable. This impact mainly applies to floating-rate home loans, where the applicable rate changes according to the benchmark and reset cycle specified by the lender. A fixed-rate home loan generally remains unaffected during the fixed-rate period. However, the rate may reset or become floating later if the loan agreement provides for such a change.

In this article, let’s discuss will home loan interest rate decrease affect your EMI, total interest cost and loan tenure, along with the options available for managing these changes.
Interest Rate and Loan Rate Fluctuations: What You Need to Know
Changes in market interest rates primarily affect floating-rate home loans when the lender applies the next scheduled reset. If the applicable rate rises, your EMI may increase, the loan tenure may extend or both may happen. If the rate falls, you may benefit through a lower EMI or shorter tenure, depending on the loan terms and the option selected.
When interest rates are low, it presents an opportunity for borrowers to avail loans at lower EMIs. On the other hand, when interest rates are high, borrowers might face higher EMIs and an increased financial burden.
The Financial Impact of Interest Rate Changes
Now that you understand the importance of interest rates and home loan rate fluctuations, let's delve deeper into the financial impact of these changes on your home loan repayments.
1. Impact on Monthly EMIs
An increase in interest rates results in higher EMIs, while a decrease leads to lower EMIs. It's crucial to factor in potential changes in EMIs when planning your monthly budget.
Example: Suppose you take a home loan of ₹50 lakhs at an interest rate of 9% for a tenure of 20 years. The equated monthly instalment (EMI) for this loan would be approximately ₹44,986. Now, let's consider the impact of a 1% increase in interest rates. With the new interest rate of 10%, the EMI for the same loan amount and tenure would increase to ₹48,251, resulting in an additional burden of ₹3,265 every month.
This example clearly demonstrates how small changes in interest rates can have a significant impact on your monthly EMIs.
2. Impact on Total Interest Paid
Interest rate changes not only impact your monthly EMIs but also affect the total interest paid over the entire loan tenure.
Example: Let's revisit our previous example of ₹50 lakhs home loan at an interest rate of 9% for 20 years. The total interest paid over this tenure would be approximately ₹ 57,96,711 . Now, if there is a 1% increase in interest rates, the total interest paid would rise to approximately ₹ 65,80,260 . This means an additional burden of ₹7,83,549 over the loan tenure.
These calculations highlight how even slight changes in interest rates can significantly impact the overall cost of your home loan.
3. Impact on Loan Tenure
Interest rate changes can also affect the tenure of your home loan. An increase in interest rates may extend the loan tenure, whereas a decrease can shorten it.
Example: Continuing with our previous example of a home loan of ₹50 lakhs at an interest rate of 9% for 20 years, with an increase of 1% in interest rate and the same EMI amount, the loan tenure will extend to approximately 26 years.
You can use a home loan calculator to see how your EMI changes at different interest rates and compare total interest payable and overall repayment amount.
Strategies to Manage Interest Rate Changes
Some strategies to help you manage loan rate fluctuations effectively are:
Final Thoughts
In conclusion, interest rate changes can have a significant impact on your home loan repayments and overall financial planning. Understanding these dynamics is crucial for making informed decisions regarding your loan repayment strategy.
Ujjivan SFB offers a range of reliable financial solutions, including Home Loans, that can help you navigate through the challenges presented by interest rate changes.
Disclaimer:
The contents herein are only for informational purposes and generic in nature. The content does not amount to an offer, invitation or solicitation of any kind to buy or sell, and are not intended to create any legal rights or obligations. This information is subject to updation, completion, amendment and verification without notice. The contents herein are also subject to other product-specific terms and conditions, as well as any applicable third-party terms and conditions, for which Ujjivan Small Finance Bank assumes no responsibility or liability.
Nothing contained herein is intended to constitute financial, investment, legal, tax, or any other professional advice or opinion. Please obtain professional advice before making investment or any other decisions. Any investment decisions that may be made by the you shall be at your own sole discretion, independent analysis and evaluation of the risks involved. The use of any information set out in this document is entirely at the user’s own risk. Ujjivan Small Finance Bank Limited makes no representation or warranty, express or implied, as to the accuracy and completeness for any information herein. The Bank disclaims any and all liability for any loss or damage (direct, indirect, consequential, or otherwise) incurred by you due to use of or due to investment, product application decisions made by you on the basis of the contents herein. While the information is prepared in good faith from sources deemed reliable (including public sources), the Bank disclaims any liability with respect to accuracy of information or any error or omission or any loss or damage incurred by anyone in reliance on the contents herein, in any manner whatsoever.
To know more about Ujjivan Small Finance Bank Products Visit:"https://www.ujjivansfb.bank.in"
All intellectual property rights, including copyrights, trademarks, and other proprietary rights, pertaining to the content and materials displayed herein, belong
to Ujjivan Small Finance Bank Limited or its licensors. Unauthorised use or misuse of any intellectual property, or other content displayed herein is strictly prohibited and the same is not intended for distribution to, or use by, any person in any jurisdiction where such distribution or use would (by reason of that person’s nationality, residence or otherwise) be contrary to law or registration or would subject Ujjivan Small Finance Bank Limited or its affiliates to any licensing or registration requirements.