UPI Update: What is the New UPI ₹2,000 Limit Rule All About?
Disclaimer: This article is for general information/education and is not investment advice. The information is shared in good faith and for general informational purposes only. Ujjivan SFB does not make any representations or warranties regarding the accuracy, completeness, or reliability of the content.
September 15, 2026
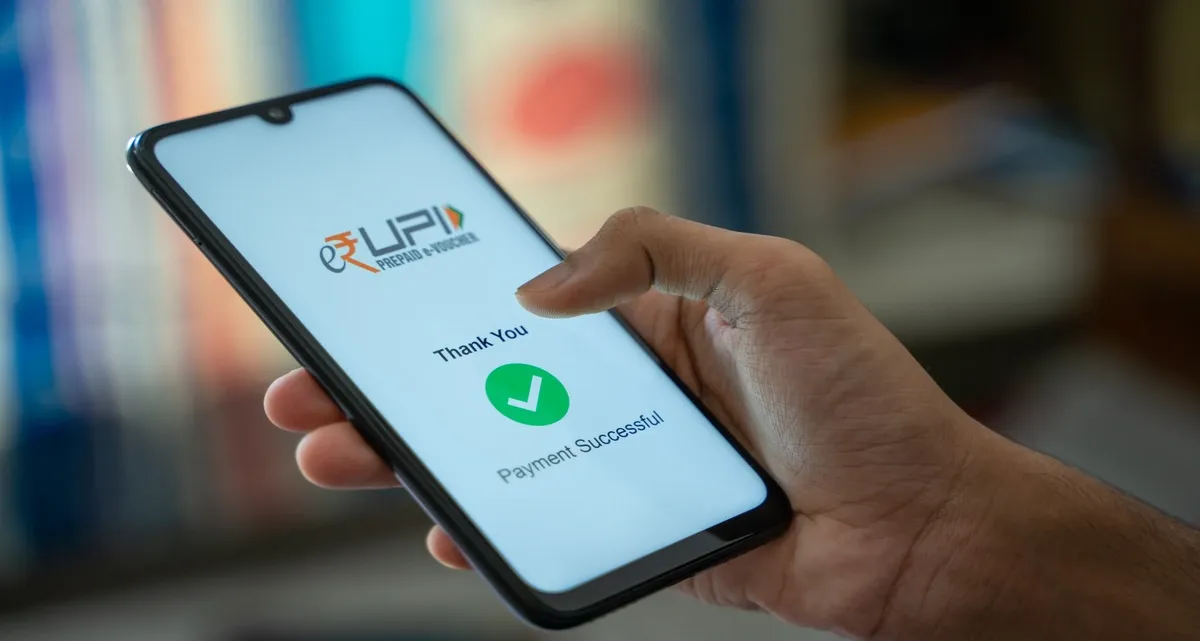
The Ministry of Finance, on September 14, 2026, released a notification stating that banks and system providers cannot impose direct or indirect charges on UPI transactions of up to ₹2,000. The notification also covers debit cards powered by RuPay.
The notification also builds on the government's August 8, 2026 clarification on UPI charges, which stated that users would not face transaction charges and P2P UPI payments would remain free.
So, what does the ₹2,000 UPI limit rule mean? Does it apply to the user or the merchant? What happens to payments above ₹2,000?
This blog explains the rule, how it can benefit you, and what you should not confuse it with.
What is the UPI no-charge rule for payments up to ₹2,000?
If you make a UPI payment of up to ₹2,000, you won't have to pay any direct or indirect charge to the bank or system provider. The same applies to electronic payments made using RuPay debit cards.

In August alone, a massive 24.51 billion transactions were made through UPI. The vast majority of these transactions are completely free of charge. Currently, the massive infrastructure costs of running the UPI system are heavily supported by the government, banks, and service providers.
To help reduce this financial burden on the ecosystem, a 0.4% MDR (Merchant Discount Rate) are apparently being discussed for certain high-value transactions.
This is not an updated UPI transaction limit or the limit for PIN-less or offline UPI payments. It is simply the transaction value up to which banks and system providers cannot impose a transaction fee or any other direct or indirect charge on the person making or receiving the payment.
Important Note: The 0.4% MDR is currently just a proposed concept for specific high-value merchant transactions, not an active or official rule. Everyday personal UPI payments remain completely free, so general users do not need to worry about any charges.
What is MDR?
MDR, or Merchant Discount Rate, is the fee charged to a merchant for processing a digital payment, particularly a debit or credit card transaction. The Reserve Bank of India (RBI) defines MDR as the rate charged to a merchant for payment-processing services on debit and credit card transactions.
For example, suppose a customer pays a shopkeeper ₹1,000 by card and the applicable MDR is 1%. The payment-processing charge would be ₹10. Depending on the commercial arrangement, the merchant would effectively receive ₹990 before considering applicable taxes or other charges.
MDR should not be confused with a single fee retained entirely by one company. The amount can cover different components of the payment ecosystem, including the acquiring bank/payment service provider, card network and card-issuing bank. RBI has therefore required acquiring banks to clearly unbundle MDR for different categories of cards to improve transparency.
Is MDR applicable to every digital payment in India?
No. The treatment depends on the payment instrument.
For debit cards, RBI prescribes maximum MDR limits. Under its December 2017 directions, the cap varies according to factors such as the merchant's turnover and whether payments are accepted through physical/online POS infrastructure or QR-code-based card infrastructure. RBI also directed banks to ensure that merchants do not pass debit-card MDR charges on to customers.
For credit cards, pricing works differently and RBI has stated that it has not issued equivalent instructions prescribing charges on credit-card transactions.
For UPI and RuPay debit-card transactions, the Government introduced a zero-MDR regime effective January 1, 2020, meaning MDR is not collected on transactions made through these prescribed modes. RBI's official payments-system assessment also records this position.
What Happens to UPI Transactions Above ₹2,000?
The new notification mentions charges for UPI transactions up to ₹2,000. For transactions above ₹2,000, we also need to look at the government's August 8, 2026 PIB clarification.
Taken together, both notifications mean that:
What Should You Know About the New UPI ₹2,000 Rule?
There are a few things you should know about the UPI no-charge rule:
Final Thoughts
The new UPI no-charge rule for payments up to ₹2,000 is a useful step towards making UPI more convenient for everyday users. However, the exact applicability has not been rolled out yet, so nothing should be assumed at this stage. Look for the official notification from the government and any follow-up updates from your bank or UPI app before making any assumptions about the charges.
Disclaimer:
The contents herein are only for informational purposes and generic in nature. The content does not amount to an offer, invitation or solicitation of any kind to buy or sell, and are not intended to create any legal rights or obligations. This information is subject to updation, completion, amendment and verification without notice. The contents herein are also subject to other product-specific terms and conditions, as well as any applicable third-party terms and conditions, for which Ujjivan Small Finance Bank assumes no responsibility or liability.
Nothing contained herein is intended to constitute financial, investment, legal, tax, or any other professional advice or opinion. Please obtain professional advice before making investment or any other decisions. Any investment decisions that may be made by you shall be at your own sole discretion, independent analysis and evaluation of the risks involved. The use of any information set out in this document is entirely at the user's own risk. Ujjivan Small Finance Bank Limited makes no representation or warranty, express or implied, as to the accuracy and completeness of any information herein. The Bank disclaims any and all liability for any loss or damage (direct, indirect, consequential, or otherwise) incurred by you due to use of or due to investment, product application decisions made by you on the basis of the contents herein. While the information is prepared in good faith from sources deemed reliable (including public sources), the Bank disclaims any liability with respect to accuracy of information or any error or omission or any loss or damage incurred by anyone in reliance on the contents herein, in any manner whatsoever.
To know more about Ujjivan Small Finance Bank Products Visit:"https://www.ujjivansfb.bank.in"
All intellectual property rights, including copyrights, trademarks, and other proprietary rights, pertaining to the content and materials displayed herein, belong to Ujjivan Small Finance Bank Limited or its licensors. Unauthorised use or misuse of any intellectual property, or other content displayed herein is strictly prohibited and the same is not intended for distribution to, or use by, any person in any jurisdiction where such distribution or use would (by reason of that person's nationality, residence or otherwise) be contrary to law or registration or would subject Ujjivan Small Finance Bank Limited or its affiliates to any licensing or registration requirements.
Explore Our Products